

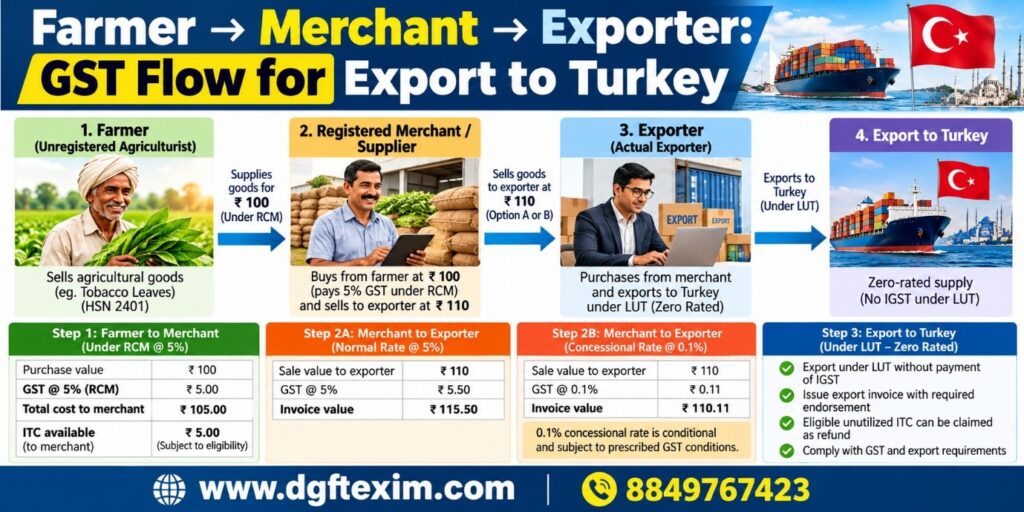
When an exporter purchases agricultural goods through a registered merchant and exports them to Turkey, understanding the GST flow is important. The transaction generally involves three stages: purchase from the farmer, supply by the merchant, and zero-rated export by the actual exporter.
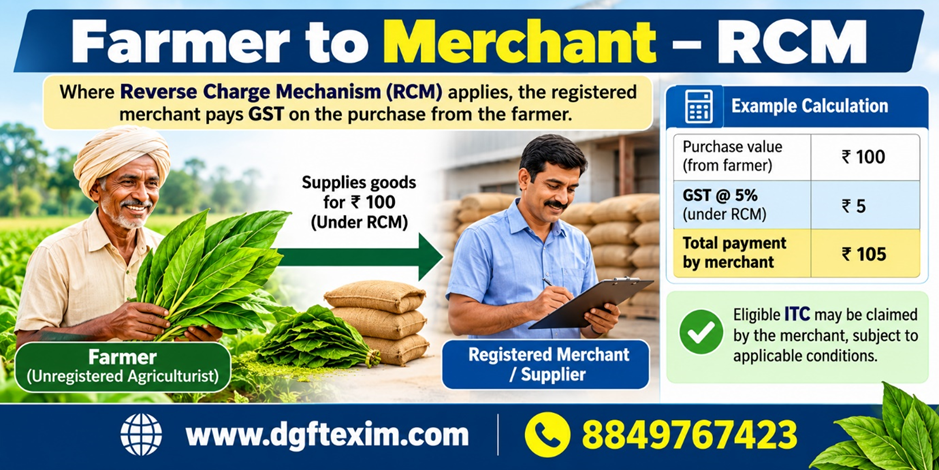
Farmer to Merchant – RCM
Where Reverse Charge Mechanism (RCM) applies, the registered merchant pays GST on the purchase from the farmer.
Example:
Purchase value: ₹100
GST @ 5% under RCM: ₹5
Eligible ITC may be claimed by the merchant, subject to applicable conditions.
Merchant to Exporter
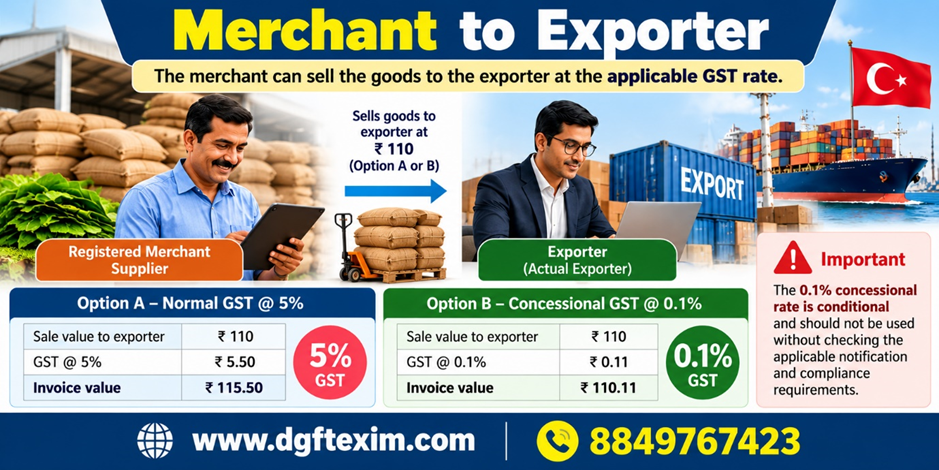
The merchant can sell the goods to the exporter at the applicable GST rate.
For example, on a sale value of ₹110:
- Normal 5% GST: ₹5.50
- Concessional 0.1% GST: ₹0.11, where all prescribed conditions are fulfilled.
The 0.1% concessional rate is conditional and should not be used without checking the applicable notification and compliance requirements.
Export to Turkey Under LUT
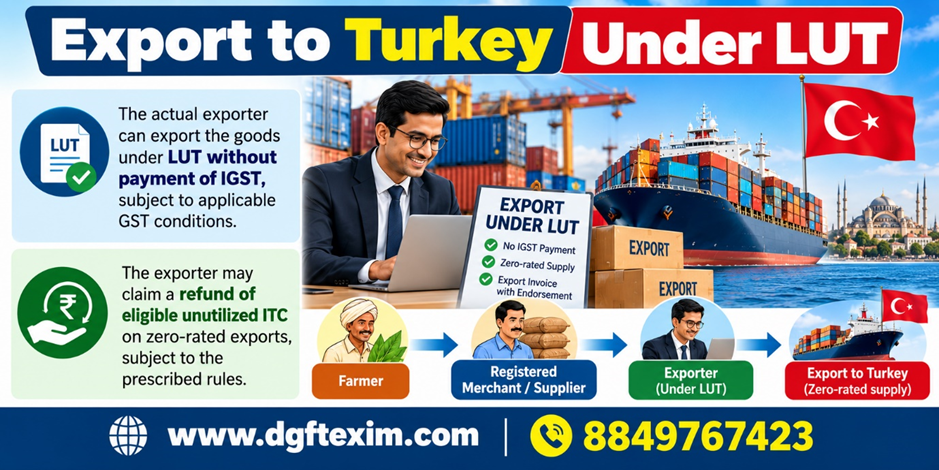
The actual exporter can export the goods under LUT without payment of IGST, subject to applicable GST conditions.
The exporter may claim a refund of eligible unutilized ITC on zero-rated exports, subject to the prescribed rules.
Conclusion
The GST flow from Farmer → Registered Merchant → Exporter → Turkey can involve multiple tax and compliance stages.
The key point is that RCM on the farmer-to-merchant purchase, ITC, the normal GST rate or concessional 0.1% procurement route, LUT-based export and refund of eligible unutilized ITC should be examined separately.
The 0.1% concessional mechanism is conditional, so exporters should verify the product, transaction structure and all applicable notification conditions before adopting it.
Disclaimer: This article is for general educational purposes. GST treatment can vary based on the product classification, nature of supply, registration status and applicable notifications/rules. Obtain transaction-specific professional advice before implementation.